


BOSS Money Transfer. Send Cash
4.827.57K Reviews
App Specs
- Version
- 26.7.1
- Updated On
- License
- Free
- Downloads
- 1,000,000+
- Developer
- Boss Revolution
- Categories
- Finance
- Platform
- Android, iOS
Screenshots
 Analysis by AppCompare
Sending money across borders is one of those jobs where convenience matters, but convenience alone is not enough. I want to know what I will pay, how the exchange rate affects the recipient, whether the process is easy to repeat, and whether the app suits the way my family actually receives money. I spent time looking at BOSS Money Transfer as a practical finance app rather than treating it like a simple download recommendation. My overall impression is that it is most useful for people who regularly send remittances and want a dedicated mobile workflow instead of relying on a bank branch or a general payment app.
Developed by Boss Revolution, the app is free to install and is aimed at Everyone. It has been available since November 21, 2016, and the current version is 26.7.1 for devices running OS 8.1 or later. Its position in the market is clear: this is not a budgeting tool, an investment dashboard, or a digital wallet designed around everyday shopping. It is a focused way to arrange international money transfers, with low fees and exchange rates presented as central reasons to consider it.
How I would decide whether BOSS Money Transfer fits
I’d judge the fit by running one careful, non-urgent transfer through the whole process, from entering recipient details to confirming that the money is accessible. That gives me a better sense of the real effort than an initial look at the screens, and it helps separate a convenient routine from a one-time novelty. I’d also consider whether the recipient is comfortable with the method, since their experience is part of whether the app deserves a lasting place on my phone.
Start with the recipient, not the interface
The first question I would ask is how the person on the other end expects to receive money. A remittance app can feel excellent to the sender and still be inconvenient if the recipient prefers a different delivery method or needs a particular form of access. Before creating a transfer, I would confirm the recipient’s preferred route, the information they need to provide, and whether they can collect or access the funds comfortably. That small conversation can prevent a transfer from becoming a support problem later.
This is also why I would not judge the app only by how quickly I can move through its screens. The important result is a successful handoff. If you send money often to the same person, a dedicated remittance service can become easier than rebuilding the process through a bank each time. If you send money only once, the setup and identity checks may feel like more work than expected, especially compared with an existing payment service you already use.
Look at the complete cost
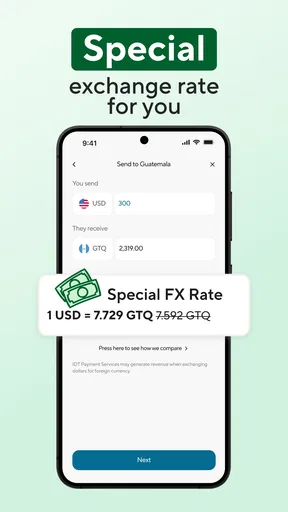
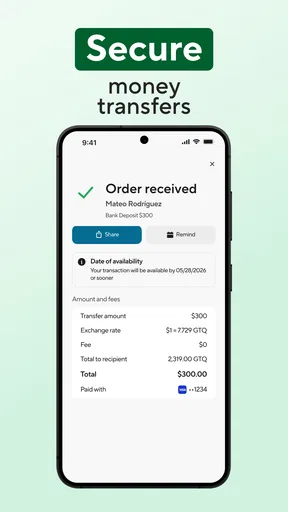
A low visible fee is only one part of the decision. I would compare the final amount received, not merely the amount charged to my card or bank account. The exchange rate can change the value that reaches the recipient, so I would review the transfer summary carefully before confirming. BOSS Money Transfer is built around low fees and favorable exchange rates, which gives it a strong starting point, but the useful comparison is always the final recipient amount for the exact route and payment method I need.
My practical habit would be to take a screenshot or note of the quoted total before sending, then compare it with one or two familiar alternatives at the same moment. Rates and fees can vary by destination, funding method, and transfer details. This is not a criticism unique to this app; it is simply the part of remittances that is easiest to overlook when an attractive headline fee grabs attention.
Worth Reading Before You Choose

EA SPORTS FC Mobile 26 Is a Bigger Football Game, but It Takes Time

Flipboard Shows What News Apps Must Do Beyond the Feed

Switching to Android Auto Means Rethinking Your Driving Routine

Google Calendar Makes a Crowded Week Easier to Manage

Ludo King Makes the Most of the Minutes Between Plans

Baby Panda World Brings Quick Play to Modern Phones, but Its Game Library Feels Busy
Separate recurring needs from one-off needs
For recurring family support, the app makes more sense than it does for a single emergency experiment. A repeat sender benefits from learning the workflow once, keeping recipient details organized, and developing a routine for checking the final quote. I would use a consistent checklist: verify the recipient’s name, check the amount they should receive, review the exchange rate, and save the confirmation. That routine is more valuable than rushing through a familiar-looking screen.
For a one-time transfer, I would first ask whether my bank, a cash-transfer provider, or another payment app already offers the exact destination and delivery option I need. The best choice may be the service that the recipient already understands. BOSS Money Transfer becomes more compelling when its remittance focus solves a repeated problem rather than adding another account to a single-use situation.
Consider trust and repetition
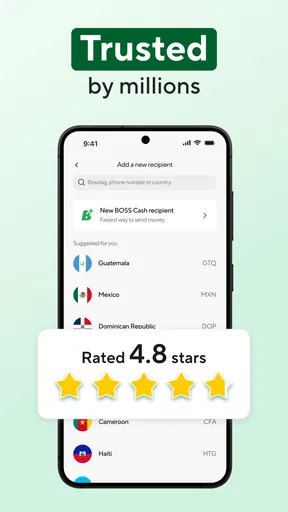
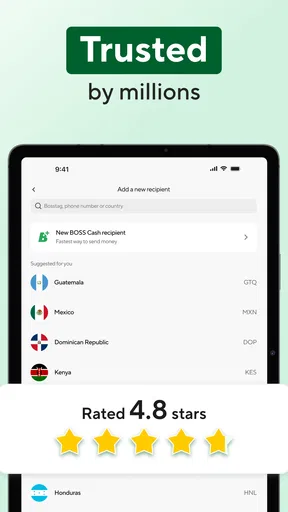
A finance app needs to feel dependable enough for repeated use. BOSS Money Transfer has a 4.8 average from around 57 thousand ratings, with more than 1 million installs. Those figures suggest that many people have made it part of their transfer routine, although popularity should not replace checking the details of your own route. I would still read the confirmation screen every time, particularly when sending a larger amount or transferring to a new recipient.
The app’s long presence in the category also matters to me. It was released in 2016, so it is not a brand-new service asking users to trust an untested concept. That does not guarantee that every transfer will be frictionless, but it does make the product easier to consider for someone who wants a dedicated remittance name rather than an unfamiliar experiment.
Where the focused design helps
The strongest part of the experience is its narrow purpose. When I open a remittance app, I do not have to sort through investment charts, shopping features, or a crowded social feed before reaching the task. That focus makes the product easier to explain to a family member: install the app, prepare the recipient information, review the quote, and keep the confirmation after sending.
That simplicity is particularly useful for people who live in one country while supporting relatives in another. It also suits users who do not want to visit a physical location for every transfer. The free price removes an initial barrier to trying the service, while the finance-focused design keeps the main decision centered on the transfer itself rather than on unrelated features.
A useful workflow for monthly support
Imagine that I send money home near the end of every month. I would begin by checking the recipient’s current details rather than assuming last month’s information is still correct. Then I would enter the amount, inspect the fee and exchange-rate information, and focus on the amount the recipient is expected to receive. Before confirming, I would read the recipient name character by character. Afterward, I would keep the confirmation until the recipient confirms that the money arrived or became available.
The non-obvious advantage of this routine is that it turns the app into a controlled process instead of a quick tap-through. A transfer app is not just a calculator; it is part of a chain involving two people, two locations, and sometimes different expectations about timing and access. Using the same verification steps each month reduces the chance that convenience will lead to a preventable mistake.
Good exchange rates need active checking
Because exchange rates are central to the service’s appeal, I would treat the quote screen as the most important part of every transaction. I would not assume that a previous transfer’s rate still applies, and I would avoid comparing a BOSS quote from one day with a competitor’s quote from another. The fair test is to enter the same send amount and destination in both services at roughly the same time, then compare what the recipient would receive after all visible charges.
This is one of the places where the app can reward an attentive user. Someone who simply presses through may miss the difference between the amount paid and the amount delivered. Someone who pauses for a few seconds can make a better decision. The recipient’s final amount is the number I would use to judge value.
What may slow the experience down
Remittance services must protect transfers, so a new user should expect the process to involve more verification than sending a casual message or paying a friend for lunch. I would have the necessary personal and recipient information ready before starting. If I were under time pressure, I would avoid beginning a transfer moments before the money is needed. Preparation matters because a missing detail or an unfamiliar verification step can make a supposedly quick payment feel stressful.
Another possible friction point is that the best route for one recipient may not be the best route for another. The app’s usefulness depends on the destination and the recipient’s circumstances, so I would not assume that one successful transfer automatically makes it the perfect answer for every country or family member. The product is focused, but international money movement is still dependent on the details of each transaction.
When a bank or general payment app may be better
A bank transfer may suit someone who already has a strong international banking arrangement and values keeping every transaction inside one established account. A general payment app may be more convenient when both people already use it for everyday payments and the transfer is small or informal. A cash-transfer provider with a nearby physical location may be preferable when the recipient needs in-person access or is uncomfortable using mobile services.
I would also look elsewhere if I needed a broader financial toolkit. BOSS Money Transfer is not the app I would choose for tracking spending, building a household budget, managing investments, or organizing several types of accounts. Its specialization is a benefit for remittances, but it is also a boundary. Users wanting one app for their entire financial life may prefer a banking platform, even if that platform is less focused on international transfers.
Who should skip it
I would skip this app if I rarely send money abroad and already have a trusted, cost-effective method that the recipient prefers. Downloading another finance app for one occasional transfer may not justify the setup. I would also hesitate if the recipient cannot comfortably use the available delivery process or if the destination and payment arrangement do not match my needs.
It is also not the right choice for someone who wants a speculative investment app, a personal finance organizer, or a shopping wallet. The category matters here. This is a remittance tool first, and choosing it for a job outside that purpose would create the wrong expectations.
The real cost of switching
Moving from a bank or another remittance provider is not only about comparing fees. I would need to establish a new habit, check how recipient information is handled, and make sure the person receiving the money understands what to expect. For a regular sender, the first transfer is the time to test the complete process with an amount that is manageable if an unexpected delay or correction is required.
I would not delete my old method immediately. Keeping a backup option during the first few transfers is sensible, particularly when family support is time-sensitive. Once I know how the app behaves for my destination and the recipient is comfortable with the process, switching becomes less risky. The effort is worthwhile when the new workflow consistently produces a better recipient amount or a more convenient experience.
There is also a record-keeping cost. I would save confirmations and label them clearly with the recipient and month. That makes it easier to answer questions later and prevents confusion when several transfers have similar amounts. The app can make sending easier, but it does not replace the user’s responsibility to maintain a simple personal record.
Privacy and device habits I would use
Because this is a finance app, I would install it only from the official app marketplace, keep my phone’s operating system supported, and avoid starting a transfer on a shared or public device. I would use a strong device lock and never send account or verification details through casual messages. These habits are not glamorous, but they matter more than saving a few seconds during setup.
I would also check the recipient details in a private setting. A crowded bus or workplace is a poor place to read financial information aloud or show a transfer screen. After sending, I would keep the confirmation securely and avoid posting screenshots where personal details could be exposed. The app’s Everyone age rating makes it broadly accessible, but younger or inexperienced users still need an adult-level understanding of financial privacy.
How the app compares by category
Compared with a traditional bank, BOSS Money Transfer feels more purpose-built for remittances and may be easier for a sender who does not want to navigate a full banking interface. Compared with a general payment app, it is more clearly centered on sending money internationally rather than splitting meals or paying local contacts. Compared with a cash-based service, it favors a mobile workflow and may be less suitable for someone who wants to handle the entire transaction at a physical counter.
I would not declare one category universally superior. The right choice depends on whether the priority is a dedicated remittance experience, an existing banking relationship, broad everyday payment features, or physical assistance. BOSS Money Transfer wins when the first priority is a repeatable mobile transfer and the quoted recipient amount is competitive. It loses its advantage when the recipient’s preferred method lies elsewhere or when the user needs a complete financial hub.
My recommendation after weighing the trade-offs
I recommend BOSS Money Transfer to people who regularly support family or friends abroad and want a focused app for comparing the fee, exchange rate, and delivered amount before confirming. The combination of a free entry point, a finance-specific workflow, and a strong 4.8 average across roughly 57 thousand ratings makes it a sensible app to test. Its 26.7.1 release and OS 8.1 minimum also make the basic compatibility question straightforward for users with supported devices.
I would recommend testing it with a carefully checked, non-urgent transfer first. Confirm the recipient’s details, compare the final amount with the alternatives you already know, and keep the confirmation. If the process is convenient and the recipient is happy with the way funds arrive, the app can become a useful part of a monthly routine.
My final view is positive but practical: BOSS Money Transfer is strongest when it replaces a repeated remittance chore, not when it is chosen simply because it is free to download. I would choose it over a general payment app when international sending is the main task, but I would stay with a bank or another provider when that option better matches the recipient’s access, my existing records, or the complete amount delivered. The app earns its place by making a specific job easier; the user still needs to make the final comparison each time.
Pros
- Supports transfers to many international destinations.
- Clear fee details are shown before confirming a transaction.
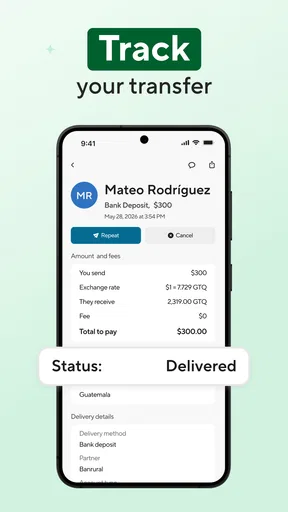
- Users can track transfer progress from the app.
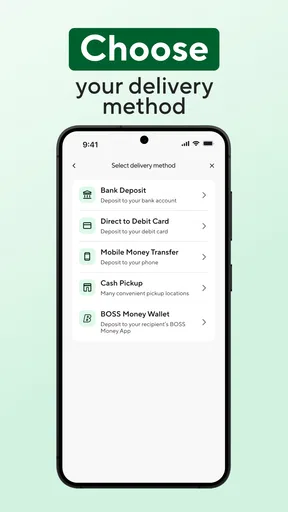
- Offers multiple delivery options in supported countries.
- Transfer receipts are easy to access for record keeping.
Cons
- Availability and features vary significantly by destination country.
- Exchange rates may be less competitive than specialist services.
- Some transfers require identity or source-of-funds verification.
- Delivery times can be affected by weekends and local holidays.
- Recipient pickup may require valid identification and matching details.
FAQs for BOSS Money Transfer. Send Cash
What is BOSS Money Transfer, and what can I use it for?
BOSS Money Transfer is a mobile service designed to help users send money internationally and, in some destinations, arrange cash pickup or delivery for the recipient. After creating an account, you can enter the destination country, choose a payment method, provide recipient details, and review the estimated exchange rate, fees, and delivery time before confirming the transfer. Availability depends on the countries and services supported.
How do I send money with the BOSS Money Transfer app?
To make a transfer, you generally need to register or sign in, verify your identity when requested, select the receiving country, enter the recipient’s information, and choose how the recipient will receive the funds. You then select an available payment option, check the total cost, and authorize the transaction. Carefully review names and account details because incorrect information can delay delivery or require a correction.
How long does a BOSS Money Transfer transaction take?
Transfer speed varies according to the destination, receiving method, payment source, compliance checks, weekends, holidays, and local banking hours. Cash pickup may be available quickly in supported locations, while bank deposits can take longer. The app normally displays an estimated delivery time before you submit the transfer. This estimate is not always a guarantee, particularly if additional verification or review is required.
What fees and exchange rates does BOSS Money Transfer charge?
The total cost can include a transfer fee and a currency exchange margin, and the amount may change depending on the destination, transfer value, payment method, and delivery option. Before confirming, review the app’s fee breakdown, exchange rate, amount sent, and amount the recipient will receive. Comparing the final delivered amount with other services is more useful than comparing the advertised fee alone.
Is BOSS Money Transfer safe, and what information is required?
The service may request personal details, identification documents, payment information, and recipient data to comply with financial regulations and prevent fraud. Use only the official app or website, protect your login credentials, and never share verification codes with another person. Confirm the recipient’s identity before sending money, and contact official customer support promptly if you notice suspicious activity or an unfamiliar transaction.


